How Mitchell Capital supports you
Comparing lender options
We compare construction loans from a wide panel of banks and lenders to find an option that suits your build.
Expert Guidance
From pre-approval to final drawdown, our brokers support you through every stage of the construction process.
Tailored Loan Structures
We help you secure flexible building loans with features like progressive payments, interest-only during construction, and offset accounts once the build is complete.
Streamlined Process
Discuss the application with Summer and request secure document access. Do not send financial details or sensitive documents by ordinary email; lender assessment and timing depend on your circumstances.
Build Your Home with Confidence
Planning to build your dream home or take on a major renovation? Getting the right finance in place is just as important as choosing the right builder. At MITCHELL. Capital, we simplify the process with tailored building loan solutions that support your project from the ground up.
What is a Building Loan?
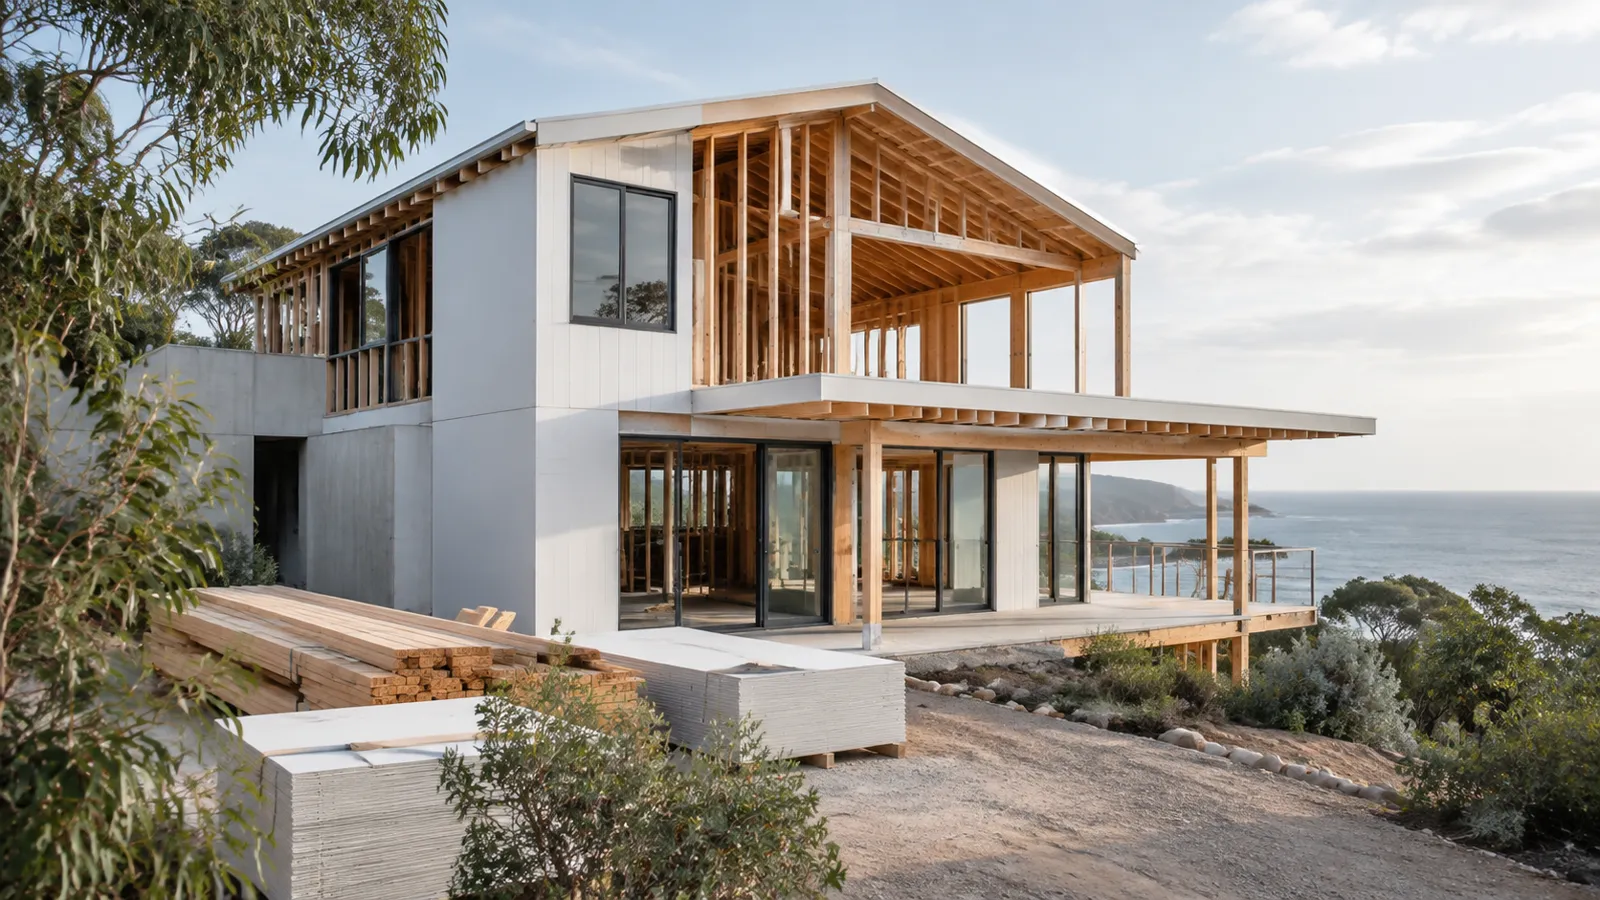
A building loan (also known as a construction loan) is a specialised type of home loan designed for people building a new home, completing a major renovation, or buying a house and land package. Unlike a traditional home loan, funds are released in stages—called progress payments—to align with each phase of your build, such as laying the slab, framing, lock-up, and final completion.
During construction, most lenders offer interest-only repayments on the amount drawn, helping to keep costs lower while the build is underway.
Why use a Building Loan?
If you’re planning to build your dream home or undertake a large renovation, a construction loan gives you the flexibility and financial control to get it done. Benefits include:
Only pay for what you use – You’re only charged interest on the funds as they’re drawn down.
Manageable cash flow – Interest-only repayments during construction help reduce pressure on your budget.
Tailored to your timeline – The loan is structured around key building milestones.
Supports home and land packages – Ideal if you’re buying land and building separately.
Explore your next step
How a construction loan works
A building loan can fund a new home, a major renovation or a house-and-land package. Instead of releasing the whole loan at once, the lender pays in stages aligned with the building contract, such as slab, frame, lock-up, fit-out and completion. During construction, many loans require interest-only payments on the amount drawn. This is subject to the lender and does not remove your obligation to repay the principal. After completion the loan generally moves to the agreed ongoing repayment structure.
Before signing a building contract
Discuss the land purchase, proposed building cost, deposit, contingency and existing housing costs together. Fixed-price contracts, approved plans, building specifications, insurance and the builder's credentials may be required. The lender usually values the completed project, not only the vacant land.
Progress payments and timing
Your builder requests payment at each agreed stage. The lender may inspect or obtain a valuation before releasing funds. Delays, variations, cost overruns and valuation shortfalls can leave you needing additional cash. Agree on how these risks will be covered before construction begins.
Loan structure through the build
Consider whether land and construction should be financed together, how interest is paid during the build, and the features you want after completion. Offset availability, extra payments and drawdown fees differ between loans.
Documents to prepare
Bring the land contract or title, building contract, plans, specifications, council approvals where available, insurance, income evidence and details of your savings and existing debts. Owner-builder and extensive renovation projects need a separate policy discussion.