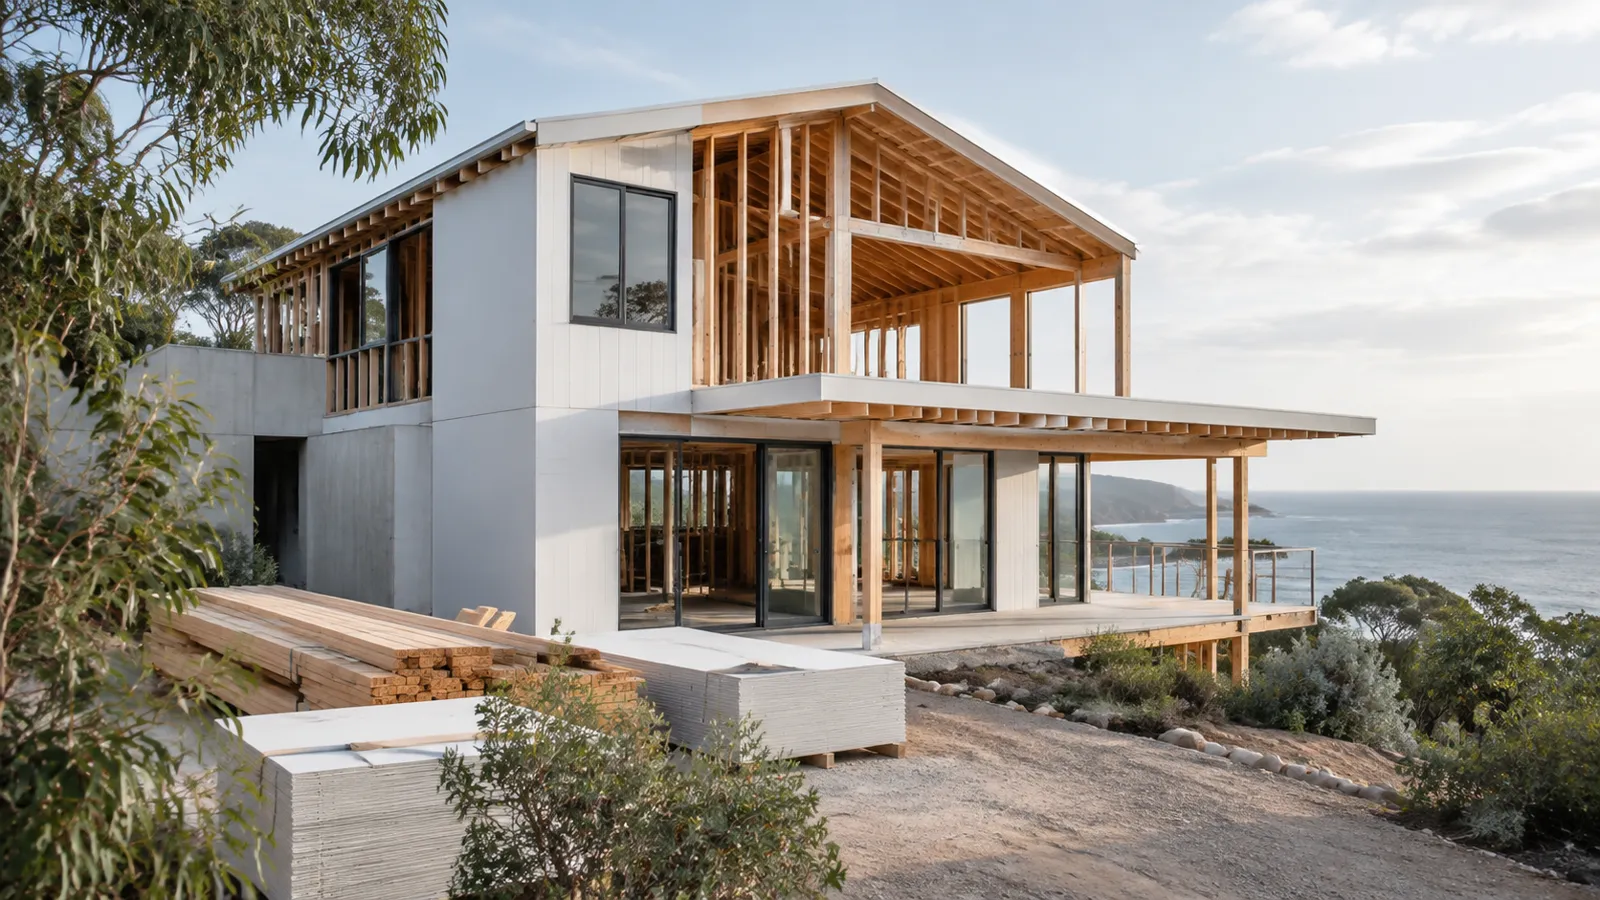
Land, construction and the completed home
These are separate milestones. Loan approval may require both the land purchase and the building contract to be assessed, with a valuation based on the proposed completed property.
The drawdown sequence
Progress payments commonly follow deposit, slab, frame, lock-up, fit-out and completion stages. The actual schedule is set by your contract and lender. Do not assume a builder's invoice means the lender will immediately release money.
Budget beyond the contract price
Allow for site preparation, connections, landscaping, variations, valuation and inspection fees, rent or an existing mortgage during the build, and a contingency. A lower completed valuation may affect the amount the lender will advance.
Interest during construction
Interest is normally calculated on funds already drawn. Interest-only payments may apply during construction, then increase once principal repayments start. Ask for a repayment estimate at full drawdown, not just at the first stage.
Changes and completion
Ask the lender before changing a contract or builder. At completion, final inspections, insurance and occupancy documentation may be needed. Confirm when the loan converts to the ongoing home loan and which features become available.